Many company plans let staff add a spouse and children. Here is which covers can include them, who counts, who pays and when to add them.
Insurers call this dependants' cover. Each insurer sets its own rules, so below is what we typically see across the market. On every quote we prepare, we set each insurer's rules out side by side.
Which covers can include family
Hospital cover is the usual starting point (what hospital cover pays), and many plans extend GP (family doctor), specialist and dental cover too. Some plans also offer life, critical illness and accident cover for family members. That can need a minimum number of insured people, such as five, and a family member's cover amount may be capped, for example at half the employee's.
One choice can force another. Some plans require dependants to take the GP and specialist add-ons if employees have them. On those plans, if your staff have GP cover, their families cannot have hospital cover alone.
Who counts as family
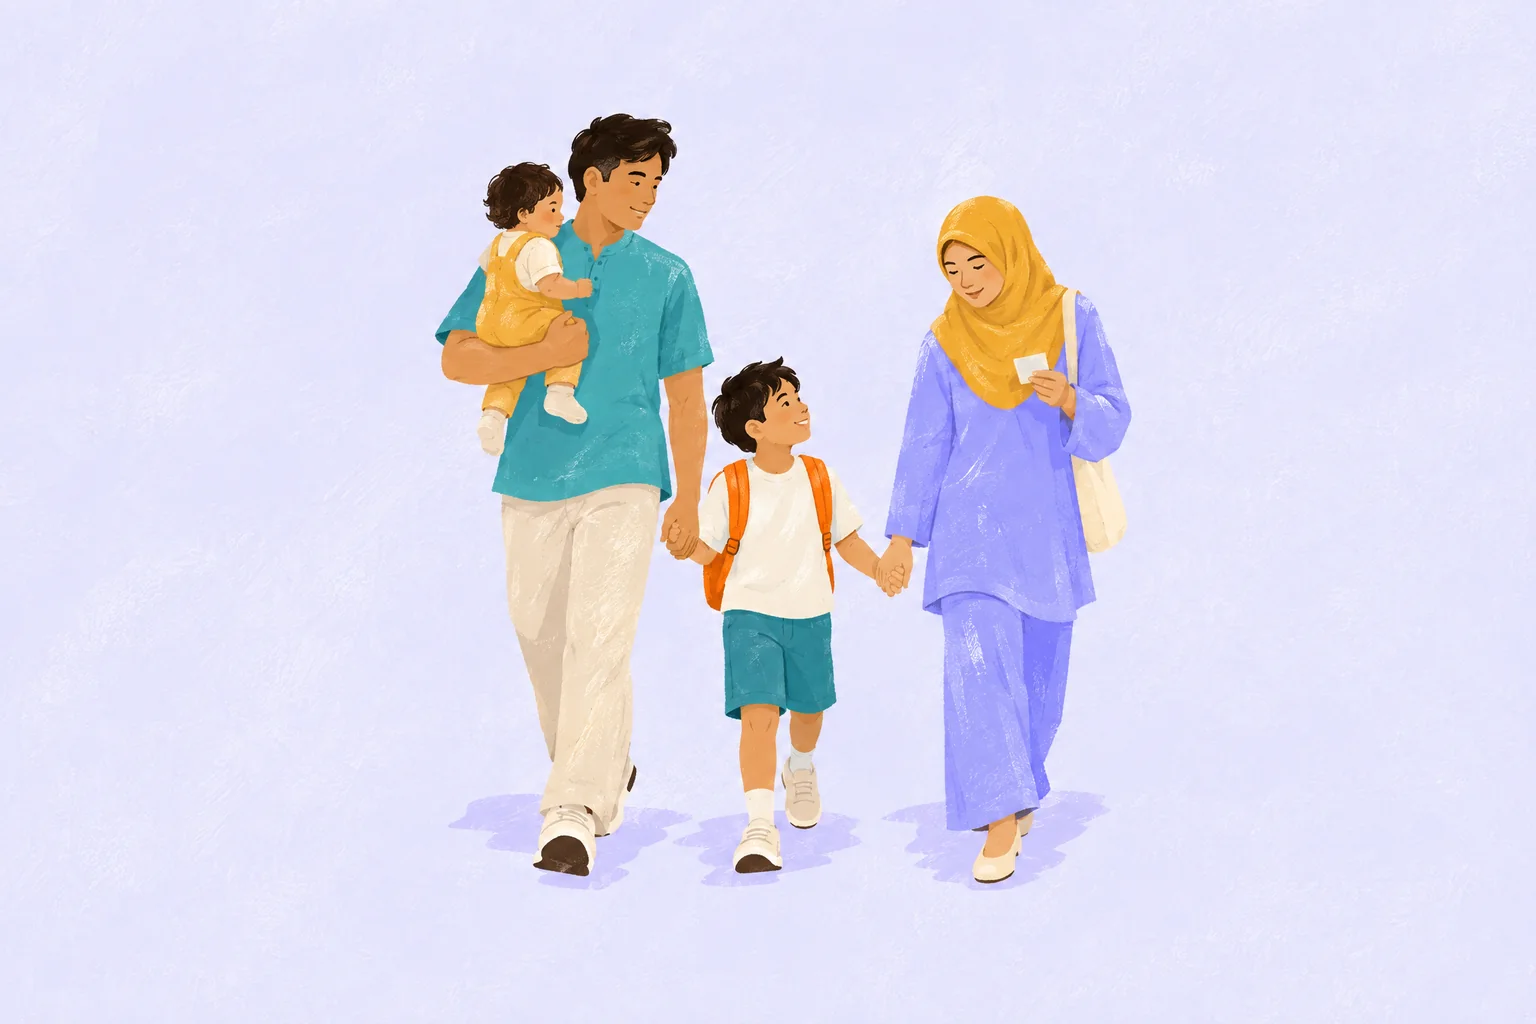
Family usually means a legal spouse and children within an age band. Children are typically accepted from 15 days old up to their mid-20s (24 or 26 are common cut-offs) if they are unmarried and not working, and some plans also exclude children serving full-time National Service. Some plans accept spouses up to age 70.
Some insurers ask for legal proof of the relationship and accept only dependants based in Singapore.
Who pays
You can pay for family cover, ask employees to pay, or split it. Our cost guide covers how dependants are priced.
Some insurers tie family cover to a whole group: if you allow dependants, it becomes compulsory for all eligible employees in the same category. That can mean every employee must enrol their family, or only that all must be offered it, and the cost differs a lot. We make sure this is clear on the quote before you commit.
If employees pay through payroll, the rules on salary deductions from the Ministry of Manpower (MOM) apply to staff covered by the Employment Act. The employee must agree in writing and be able to withdraw that consent at any time, and there are extra steps for work pass holders, including telling MOM.
Decide in advance what happens if someone stops paying mid-year.
When family can join, and health questions
Dependants can usually be added when the employee joins or at renewal. Adding someone after a marriage or birth, the deadline for doing so and removing a dependant all follow rules that vary by plan. We confirm them for your plan and make the changes with the insurer for you.
Some plans ask family members health questions in certain cases, for example for older dependants (above 65 is one threshold) or for higher life or critical illness cover amounts. Pre-existing condition rules apply to dependants as they do to employees: a common pattern is that a condition the person already had is excluded for the first 12 months of continuous cover, and some conditions, such as cancer and kidney conditions, can stay excluded permanently.
Compare with the family's own cover first
A spouse may already have a company plan of their own, and Singapore Citizen and Permanent Resident family members already have MediShield Life. Company family cover is tied to the employee's job, so treat it as an extra layer, not a reason to cancel personal plans (how the layers fit).
Decide which covers family can join and who pays, then ask us for quotes with and without family cover to see the difference.
Sources checked 23 October 2026.