If your office contents are insured for less than they would cost to replace, the insurer can cut a claim in proportion, even a small one.
Insuring below the true value is called underinsurance, and the rule that cuts the claim is the average clause. Most property policies pay an underinsured claim only in proportion to how much you insured.
How the cut works
A simplified, hypothetical example. Your desks, computers and pantry equipment would cost S$150,000 to replace today, but the policy still shows S$90,000, the figure from when you moved in. A small fire damages S$20,000 worth of them.
You insured 60% of the true value (S$90,000 of S$150,000), so the insurer pays 60% of the loss: S$12,000. You carry the other S$8,000, plus any excess (the part of each claim you pay yourself).
Wordings vary. Some small-business packages apply the average clause only when the amount insured is below 85% of the replacement cost, which gives you some room. Many also test each item on the policy separately, so a surplus on furniture does not make up for a shortfall on stock.
Use today's replacement cost
The figure you declare, the sum insured, should normally be what it would cost to replace everything new today, not what you paid or its depreciated value in your accounts. A few policies use a different basis, and we confirm which one yours uses. The commercial property guide lists what else to settle before you ask for quotes.
Build it from a list
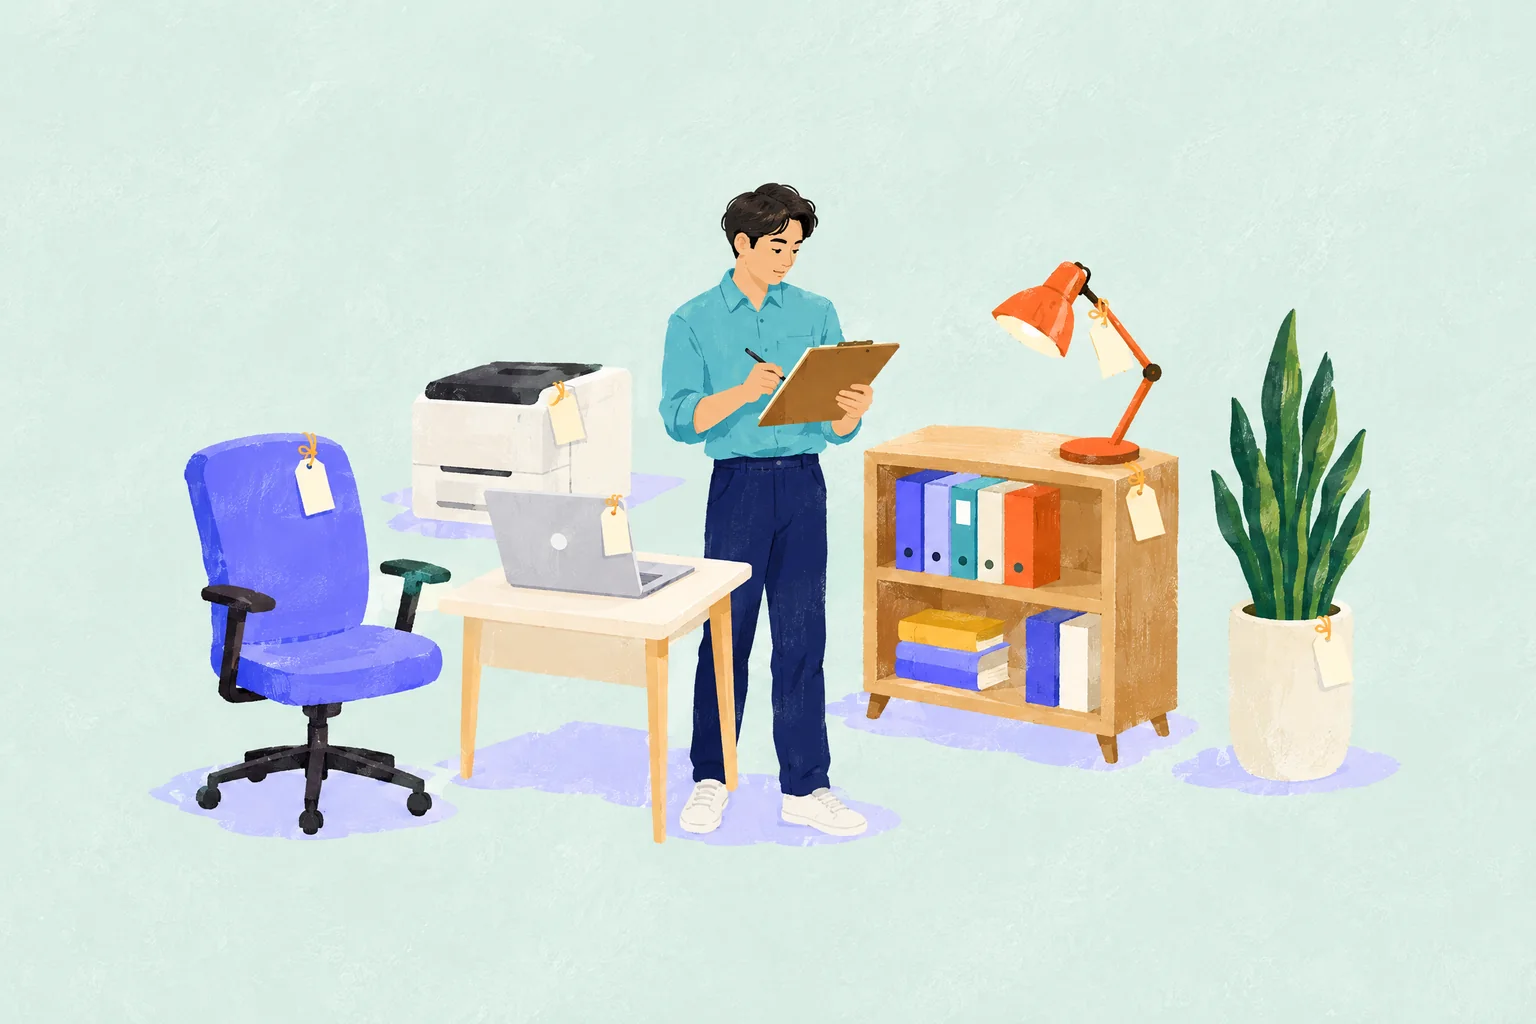
Insurers usually ask for each category separately: furniture, fixtures and fittings, office equipment, machinery and stock. Walk the office and price each group:
- Furniture: desks, chairs, storage, and meeting-room and pantry furniture.
- IT and equipment: laptops, screens, servers, phones, printers and audio-visual kit.
- Renovation you paid for: partitions, flooring, ceilings, lighting and built-in carpentry.
- Stock and samples, at the highest level you hold during the year.
Check what the lease makes yours
The lease decides who insures the building and who insures the rest. As a tenant you usually do not need to insure the premises themselves unless the tenancy agreement says so, but the contents that belong to you are yours to insure. If the lease makes you insure your renovation (the fit-out) or anything else, add it to the list.
Contents cover pays for things, not for the income you lose while closed. For that, see business interruption cover.
Keep it current
Recheck the figure at every renewal and after any big purchase, renovation or stock build-up, and tell us then rather than waiting, so we can update the insurer. The average clause is applied when you claim, so last year's correct figure can be wrong today.
Send us your list before your next renewal, and we will check it against your commercial property cover.