Most group policies run for a year, and the insurer sends renewal terms before it ends. It’s tempting to sign and move on. A short review first can keep your premium in check and your cover in step with your team.
Give yourself six to eight weeks before the policy ends. That’s enough time to ask questions, get comparison quotes and deal with any health declarations without cover lapsing.
1. Ask why the premium changed
Ask the insurer, or ask us, to explain the change. The usual reasons are:
- Claims: how much the insurer paid out compared with the premium, known as the loss ratio.
- Age: your team is a year older, and premiums for health and life cover rise with age.
- Headcount: more or fewer employees, or a different mix of ages and roles.
- Medical costs: insurers revise their rates as hospital and clinic costs rise.
- Plan changes: benefits the insurer has revised or withdrawn.
For small teams on an insurer’s package rates, the change often comes more from age and rate revisions than from your own claims. Larger teams are priced more on their own claims experience.
2. Look at your loss ratio
If the insurer shares your claims experience, work out the loss ratio: claims paid divided by premiums over the period. A company that paid S$20,000 in premiums and claimed S$16,000 has a loss ratio of 80%. A high ratio usually means a higher renewal; a low one gives you room to ask for better terms.
One large claim can skew a small team’s figures. If it was a one-off, such as an accident, say so when you negotiate.
3. Check the census
Renewal terms are based on the employee list the insurer holds. Make sure it matches reality: leavers removed, new joiners added, dates of birth and pass types correct. An out-of-date census can mean paying for people who have left, or employees who aren’t covered when they need to be.
4. Re-read the benefits
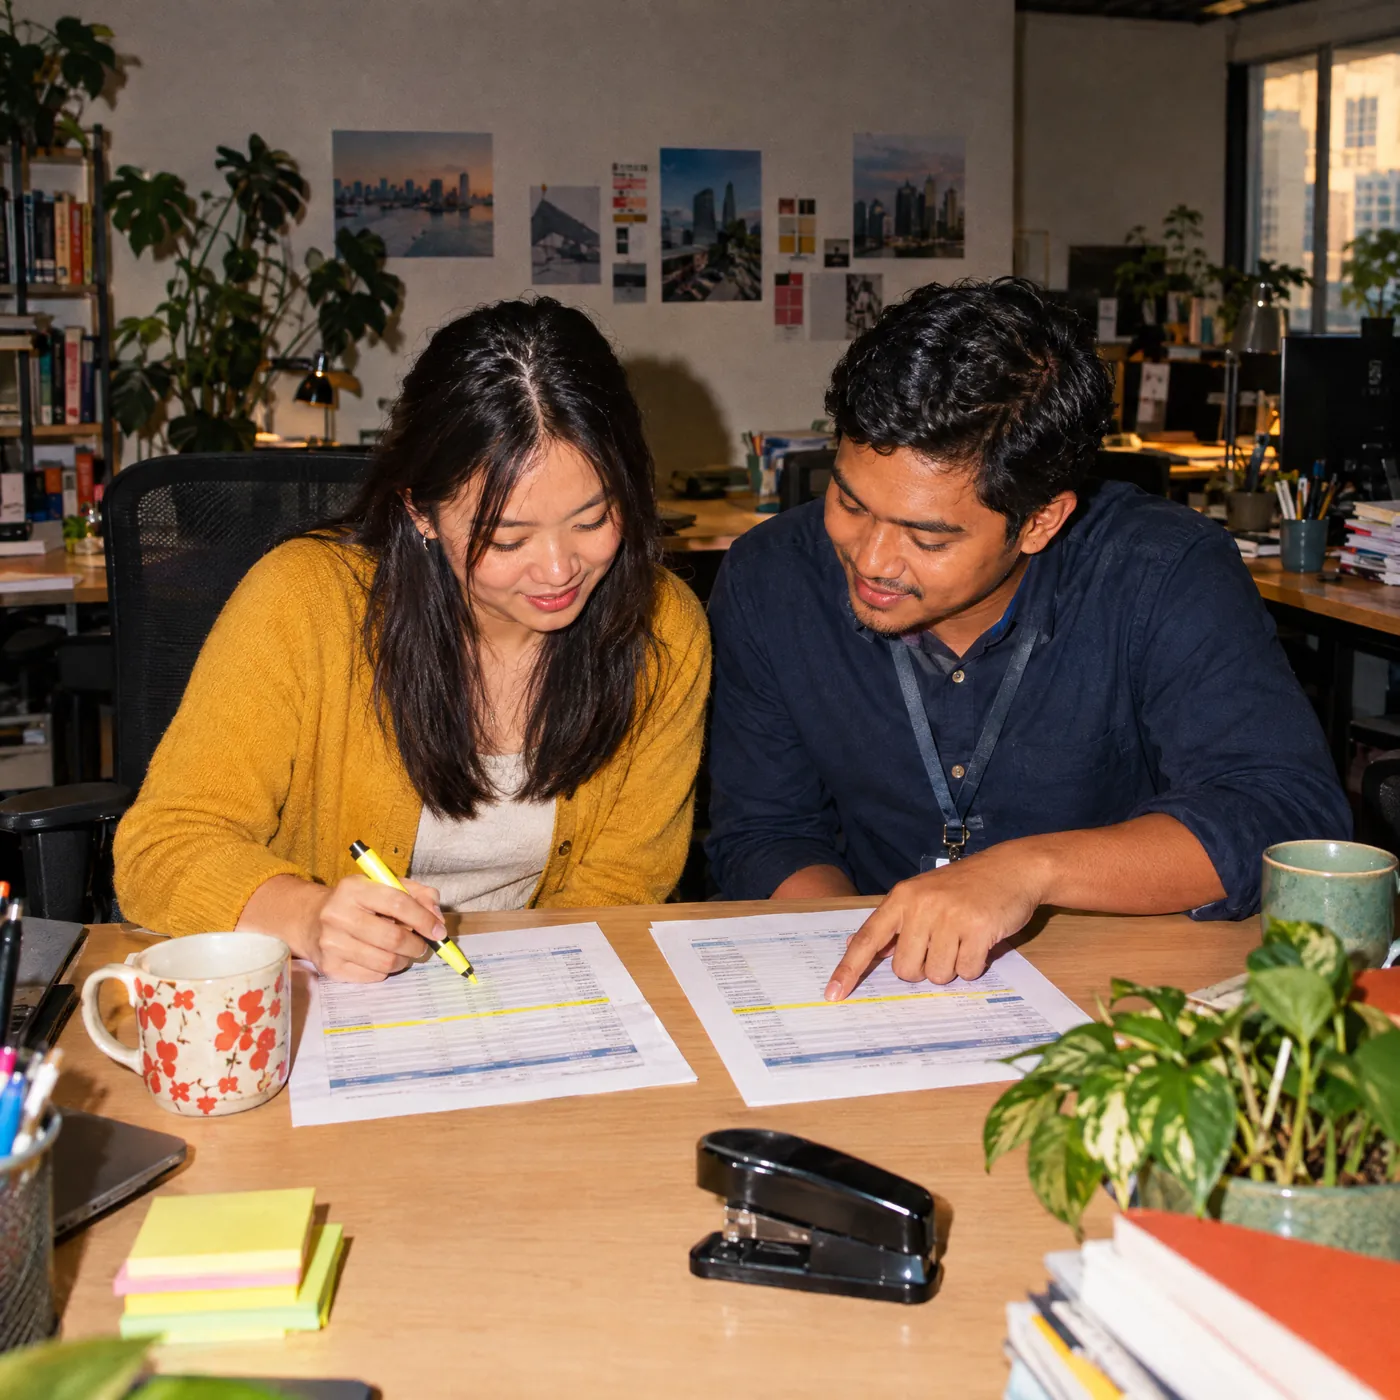
Compare the renewal schedule with last year’s, line by line. Insurers sometimes change limits, co-payments or panels at renewal. Check:
- The ward class or daily room and board limit, and the surgical limit.
- Co-payments at GP and specialist clinics.
- The clinic panel, especially the clinics your team actually uses.
- Age limits, as your employees get older.
- Term life sums insured, if salaries have moved.
5. Ask what your team uses
Talk to a few employees, or look at the claims summary if the insurer provides one. If hardly anyone uses the specialist benefit but GP visits are heavy, you might shift money from one to the other. If staff keep paying above the ward limit, the hospital plan may be set too low.
6. Get comparison quotes
Even if you’re happy with your insurer, a comparison tells you whether the renewal is fair. Other insurers can quote on your census and current benefits, and many will carry over cover for existing conditions for employees moving from your current plan without a gap. Switching isn’t always the answer, and a comparison also helps you negotiate with the insurer you have.
A renewal is a good time to ask whether your plan still fits the team you have now, not the team you had when you bought it.
7. Line up the dates
If you move, the new policy should start the day the old one ends, so no one goes a day without cover. Tell your team about any changes to cards, panels or claims before the switch date.
Send us your renewal notice and census, and we’ll compare them with other insurers on our panel and come back with quotes within the next working day.